Third Quarter 2026 Market Review
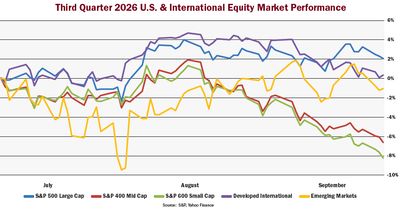
It was a challenging quarter for markets as there were headwinds from the ongoing Iran conflict, the Federal Reserve’s 1st rate increase since July 2023, and continued upward pressure on interest rates across the board. U.S. large cap stocks continued to perform well, with Info Technology and the broad Artificial Intelligence buildout showing no signs of age. Energy did well as oil markets continued to respond to Middle East fighting but West Texas Intermediate crude oil stayed below $100 for all but a few days of the quarter.
The energy impacts were more keenly felt in the mid and small cap companies as they have less pricing power to pass along higher energy/ diesel costs and they generally operate on smaller profit margins. However, for 2026 year to date, both are turning in strong performance with the S&P 600 (Small Cap) returning +12.8% and S&P 400 (Mid Cap) coming in at + 8.8%.
There are several indicators that reflect the U.S. economy has weathered this geopolitical impact and is poised to increase GDP growth by a solid amount (+0.5% to +0.7%) above earlier predictions at the start of the year— still falling short of 3% annual growth but an improvement nonetheless.
What to watch for in the 4th quarter: first, the yield on the 10-year Treasury, which is currently at the highest level in almost 20 years. This is a function of both stubborn inflationary pressures AND economic growth improving, along with a voracious demand for debt financing by the Government and the private sector. Second, earnings—it will be the indicator that growth is poised for accelerating. Finally, Iran’s domestic unrest. Indications are that their government is tightening at the same time the citizens are growing more restless. Dictatorships are strong until they aren’t… and economic pressures are building.