Second Quarter 2026 Market Review
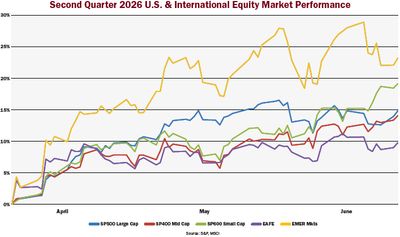
Both U.S. Domestic and International markets demonstrated incredible resilience during the quarter in light of the myriad of geopolitical events that normally would be expected to cause a significant adverse response. Here at home the S&P 500 Large Cap returned +14.8%, S&P 400 Mid Cap returned +14.1% and S&P 600 Small Cap returned +19.2%. Emerging markets led the way at +23.3% and Developed markets returned +9.7%.
The main driver in the United States was better than expected corporate earnings for Q1 2026 with 84% of the S&P 500 reporting better than estimated results. The Artificial Intelligence buildout continued unabated and we observed a broader advancement than solely the Magnificent 7. The economic sectors with the best returns were Information Technology (+33.5%) and Industrials (+15.4%). Energy declined -13.2% as the war premium began to wane. The price of a barrel of oil has returned to about $70 (where it was when the air attacks on Iran began) and that will help to temper inflation going forward.
The Federal Reserve has a new chair (Kevin Warsh) and a recent Supreme Court decision provides the Fed with more independence than other Federal commissions and agencies. This is a positive for monetary policy. We don't expect either a rate hike or cut for the remainder of 2026.